Free CXC Principles of Accounts Paper 2 May/June 2012 past paper from 2012. Includes a worked answer key. Open the PDF, take a timed test, and study with AI on Caribbean AI.
Answer keys are free on Caribbean AI. View the answers to every past-paper question at no cost - no payment needed - with step-by-step worked solutions and instant AI marking available on Premium.
CSEC Principles of Accounts Paper 2 May/June 2012 - Free CXC Past Paper with Answers
Free CXC Principles of Accounts Paper 2 May/June 2012 past paper from 2012. Includes a worked answer key. Open the PDF, take a timed test, and study with AI on Caribbean AI.
Opening the interactive papers…
Every question from this paper as text. See the answers and worked solutions. Questions are the property of the Caribbean Examinations Council; Caribbean AI is not affiliated with CXC.
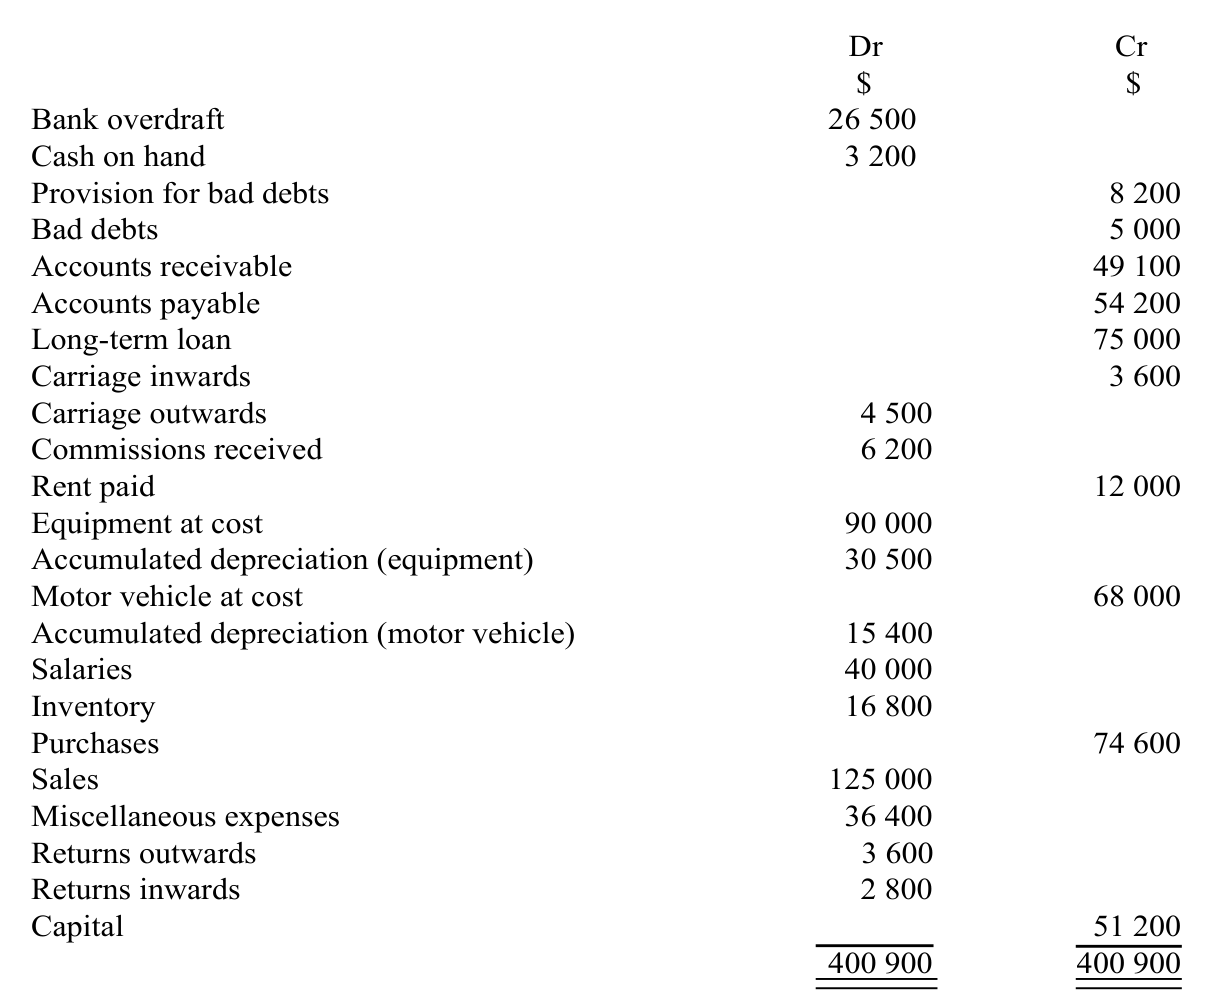
An accounting student prepared the following trial balance for Heavy Metal Enterprises for the year ended 31 December 2011 and inserted the amount of $51 200 for Capital.
| Dr | Cr |
|---|---|
| $ | $ |
| Bank overdraft | 26 500 |
| Cash on hand | 3 200 |
| Provision for bad debts | |
| Bad debts | |
| Accounts receivable | |
| Accounts payable | 54 200 |
| Long-term loan | |
| Carriage inwards | 3 600 |
| Carriage outwards | 4 500 |
| Commissions received | |
| Rent paid | 6 200 |
| Equipment at cost | 90 000 |
| Accumulated depreciation (equipment) | |
| Motor vehicle at cost | 68 000 |
| Accumulated depreciation (motor vehicle) | 15 400 |
| Salaries |
| 40 000 |
| Inventory | 16 800 |
| Purchases |
| Sales | 125 000 |
| Miscellaneous expenses | 36 400 |
| Returns outwards |
| Returns inwards | 2 800 |
| Capital |
| 400 900 |
[20 marks]
Prepare the corrected trial balance for Heavy Metal Enterprise showing clearly the correct amount for Capital.
[13 marks]
You are presented with the following day books:
| 2011 | Amount | |
|---|---|---|
| 1 September | U. Plumber | $ 7 200 |
| 4 September | V. Henry | $ 2 150 |
| 13 September | V. Henry | $ 2 100 |
| 20 September | U. Plumber | $ 3 396 |
| $14 846 |
| 2011 | Amount | |
|---|---|---|
| 3 September | U. Plumber | $ 1 000 |
| 9 September | V. Henry | $ 1 950 |
| $2 950 |
| Disc | Cash | Bank | Disc | Cash | Bank | |||
|---|---|---|---|---|---|---|---|---|
| 2011 | $ | $ | $ | 2011 | $ | $ | $ | $ |
| 1 Sept | Bal b/d | 2 645 | 10 500 | 25 Sept | Rent | |||
| 4 Sept | U. Plumber | 100 | 5 100 | 25 Sept | Wages | |||
| 24 Sept | V. Henry | 60 | 6 040 | |||||
| 30 Sept | Bal c/d | 1 945 | ||||||
| 160 | 2 645 | 21 640 | 2 645 | 21 640 |
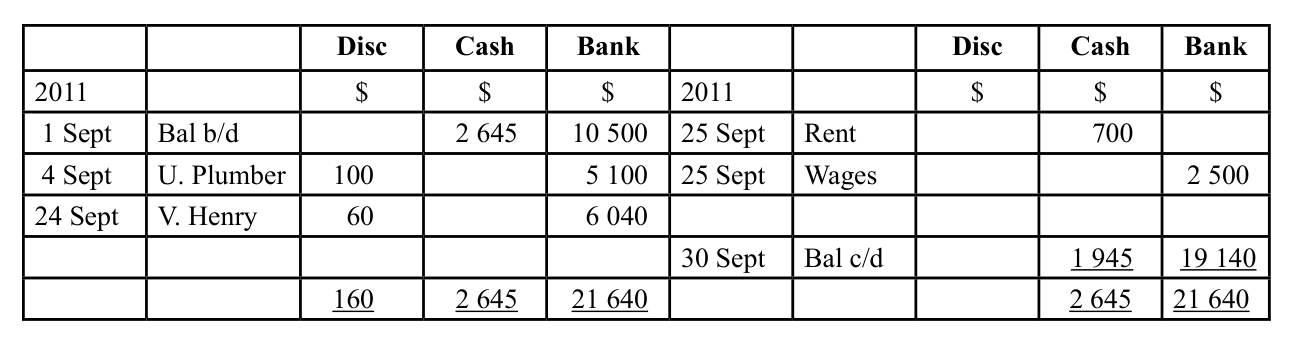
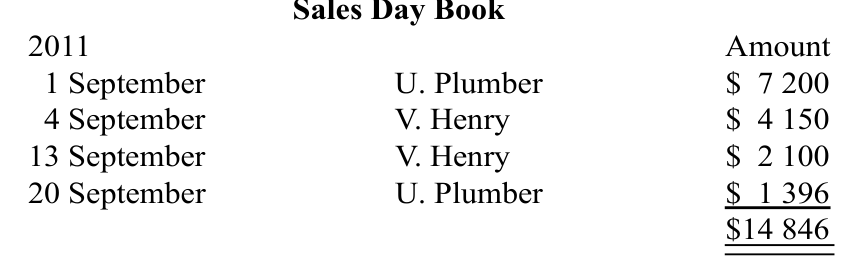
[7 marks]
Post the information from the day books in the personal account of U. Plumber and balance the account.
[3 marks]
Prepare the Debtors Control Account and any other account in the General Ledger for the month of September.
[4 marks]
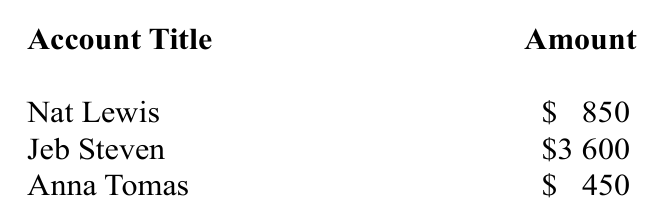
The Sales Ledger of JJ's Paradise showed the following balances at 31 December 2010.
| Account Title | Amount |
|---|---|
| Nat Lewis | $ 850 |
| Jeb Steven | $ 3 600 |
| Anna Tomas | $ 450 |
Mr JJ has decided to write off these three receivables as bad debts.
[20 marks]
The remaining receivables totalled $28 320 at 31 December 2010. Mr JJ believes that 10% of these outstanding receivables are LIKELY to become bad debts. He wishes to make adequate provision for these doubtful debts.
On 31 December 2011, Mr JJ's receivables AFTER bad debts totalled $25 000. He decided to use the same rate of 10% as the previous year in accounting for doubtful debts.
[16 marks]
Prepare the journal entry on page 5 of JJ's journal to write off the three receivables. (Narrative required)
[7 marks]
The remaining receivables totalled $28 320 at 31 December 2010. Mr JJ believes that 10% of these outstanding receivables are LIKELY to become bad debts. He wishes to make adequate provision for these doubtful debts.
Prepare the journal entry with a narrative, to create the Provision for Doubtful Debts Account.
[4 marks]
On 31 December 2011, Mr JJ's receivables AFTER bad debts totalled $25 000. He decided to use the same rate of 10% as the previous year in accounting for doubtful debts.
Draw up the Provision for Doubtful Debts Account for the TWO years, 1 January 2010 to 31 December 2011, to show the change in the provision. Balance the account at the end of EACH year.
[5 marks]
State ONE reason why adjustments are made to financial statements.
[1 mark]
Identify ONE concept which guides adjustments to financial statements.
[1 mark]
Explain how the concept identified in (b) (ii) above guides adjustments made to financial statements.
[2 marks]
V. Cheeseman is preparing his summary accounts for the month ended 31 August 2011. He finds the following errors which may or may not affect the summary of the bank account entries in his Cash Book.
Beginning with the incorrect balance of $2 570, correct the summarized Cash Book for the relevant errors given above. (Show all working.)
The bank statement for the month ended 31 August 2011 shows a balance of $5 680.
[20 marks]
V. Cheeseman is preparing his summary accounts for the month ended 31 August 2011. He finds the following errors which may or may not affect the summary of the bank account entries in his Cash Book.
[12 marks]
Prepare the journal entries to correct the errors above. (Narratives not required.)
[7 marks]
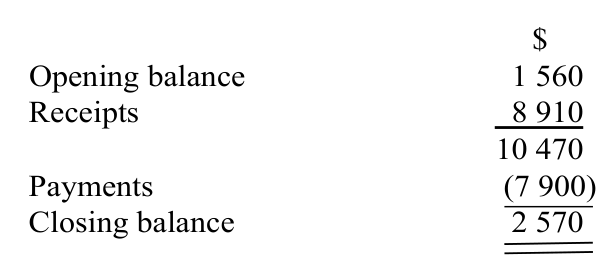
V. Cheeseman records the following figures in his summarized Cash Book BEFORE correcting the relevant errors:
| $ | |
|---|---|
| Opening balance | 1 560 |
| Receipts | 8 910 |
| 10 470 | |
| Payments | (7 900) |
| Closing balance | 2 570 |
Beginning with the incorrect balance of $2 570, correct the summarized Cash Book for the relevant errors given above. (Show all working.)
[5 marks]
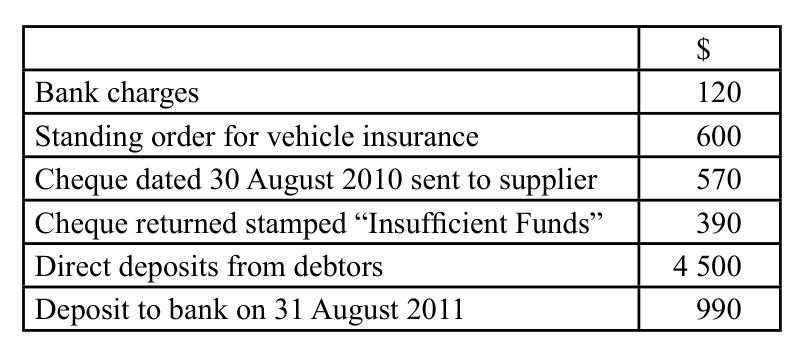
The following information is recorded in EITHER the bank statement or in V. Cheeseman's Cash Book but NOT in both.
| $ | |
|---|---|
| Bank charges | 120 |
| Standing order for vehicle insurance | 600 |
| Cheque dated 30 August 2010 sent to supplier | 370 |
| Cheque returned stamped "Insufficient Funds" | 390 |
| Direct deposits from debtors | 4 500 |
| Deposit to bank on 31 August 2011 | 990 |
The bank statement for the month ended 31 August 2011 shows a balance of $5 680.
[8 marks]
Using the corrected summarized Cash Book balance from a (ii) above, draw up an updated Cash Book for the month ended 31 August 2011.
[5 marks]
Starting with the updated Cash Book balance, draw up a Bank Reconciliation Statement for V. Cheeseman for the month ended 31 August 2011.
[3 marks]
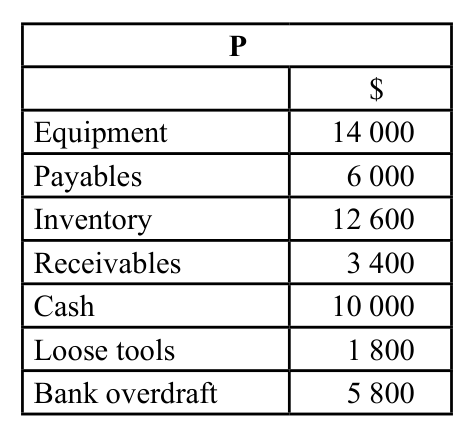
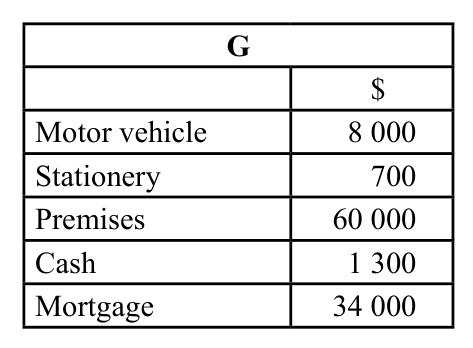
P and G are two sole traders who decided to trade under the partnership name of PG Enterprises. The following are lists of balances for EACH trader before the formation of the partnership.
| P | $ | G | $ |
|---|---|---|---|
| Equipment | 14 000 | Motor vehicle | 8 000 |
| Payables | 6 000 | Stationery | 700 |
| Inventory | 12 500 | Premises | 60 000 |
| Receivables | 3 400 | Cash | 1 300 |
| Cash | 10 000 | Mortgage | 34 000 |
| Loose tools | 1 800 | ||
| Bank overdraft | 5 800 |
[20 marks]
Prepare individual opening entries as at 1 May 2012 to record EACH sole trader's contribution to the partnership.
[7 marks]
Prepare a classified summarized Balance Sheet for PG Enterprises, as at 1 May 2012, using the order of permanence.
[7 marks]
The two partners anticipate a profit of $99 000 at the end of the first year's trading, but have not yet decided what profit-sharing ratio to adopt.
Calculate EACH partner's share of profit under the following schemes: (i) In capital sharing ratio (ii) In the ratio 3:7
Show all working.
[4 marks]
In capital sharing ratio
[2 marks]
In the ratio 3:7
Show all working.
[2 marks]
List TWO features, other than the profit sharing ratio, that should be included in P and G's partnership agreement.
[2 marks]
Explain, in ONE sentence, the meaning of EACH of the following statements:
[3 marks]
The owners of a corporation benefit from limited liability.
[1 mark]
Farris London, a shareholder, wants to know what the Board of Directors of Aries Limited does.
[1 mark]
The Registrar of Companies has received the documents required to start up the new corporation.
[1 mark]
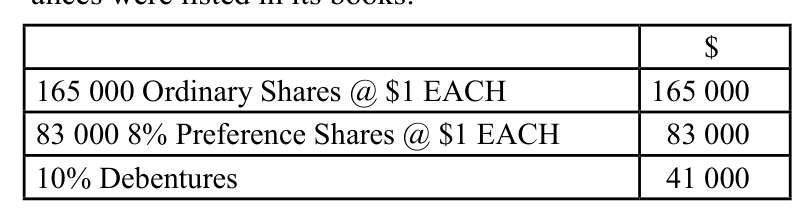
Aries Limited has an authorized share capital of 200 000 one dollar ($1) Ordinary Shares and 100 000 one dollar ($1) 8% Preference Shares. On 1 April 2011, the following balances were listed in its books:
| $ | |
|---|---|
| 165 000 Ordinary Shares @ $1 EACH | 165 000 |
| 83 000 8% Preference Shares @ $1 EACH | 83 000 |
| 10% Debentures | 41 000 |
On 1 April 2011, Aries Limited
Draft General Journal entries to record (i) the issue of the remaining ordinary shares at $1.50 EACH. (ii) the issue of the remaining preference shares at $1.00 EACH. (iii) the reduction in debentures.
Narratives not required.
[10 marks]
the issue of the remaining ordinary shares at $1.50 EACH.
[5 marks]
the issue of the remaining preference shares at $1.00 EACH.
[2 marks]
the reduction in debentures.
[3 marks]
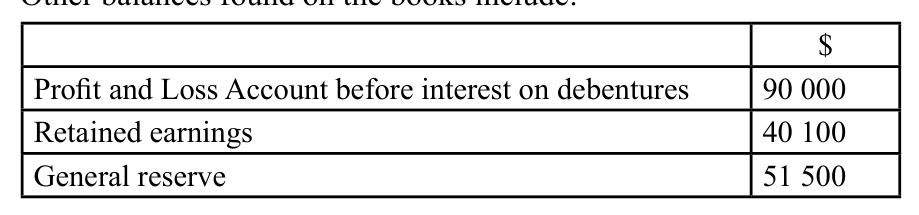
Other balances found on the books include:
| $ | |
|---|---|
| Profit and Loss Account before debentures | 90 000 |
| Retained earnings | 40 100 |
| General reserve | 51 500 |
On 31 May 2011, the directors agreed to the following:
Prepare the Appropriation Account for Aries limited for the year ended 31 May 2011. Show all working.
[7 marks]
Simon Long makes decorative concrete ornaments. He recorded the following information about his manufacturing operations for the year ended 31 December 2011.
Inventory at 1 January 2011 Direct materials $ 6 500 Indirect materials 400 Work-in-progress 12 500 Finished goods 45 000
Inventory at 31 December 2011 Direct materials $ 8 000 Indirect materials 15 100 Work-in-progress 38 400 Finished goods 70 100
Other items recorded were as follows: Purchases of direct materials 6 200 Purchases of indirect materials 2 500 Returns outwards of direct materials 1 000 Transportation costs on materials 50 000 Factory wages 12 000 Supervisory salaries 6 800 Direct expenses 5 700 Factory power 13 000 General factory expenses 3 500 Annual depreciation on factory equipment and building
Note: 90% of transportation costs relates to direct materials and 10% to indirect materials.
[20 marks]
Calculate the following costs for Simon Long:
[7 marks]
Direct materials consumed
[4 marks]
Indirect materials used
[3 marks]
Prepare the Manufacturing Account for Simon Long for the year ended 31 December 2011.
Show clearly the
[11 marks]
Calculate the cost of goods sold.
[2 marks]
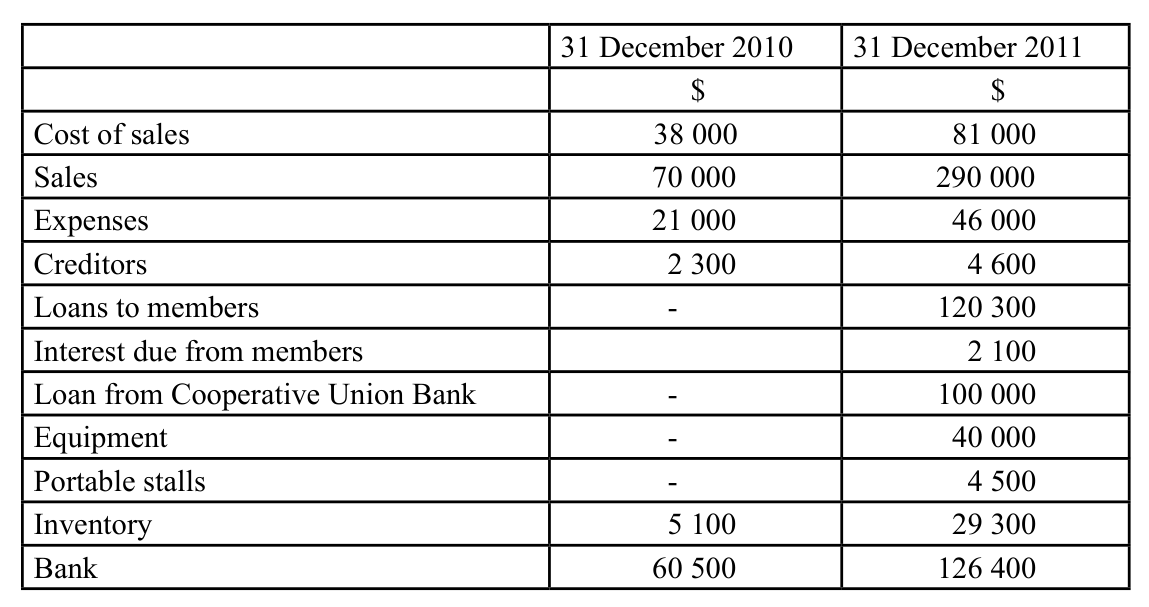
Liontown Co-operative was formed to produce souvenirs for the booming tourist market. The co-operative started with share capital of $55 000 in $1 shares. The co-operative is now two years old and records the following information for the first two years of operation.
| 31 December 2010 | 31 December 2011 | |
|---|---|---|
| Cost of sales | 38 000 | 81 000 |
| Sales | 70 000 | 290 000 |
| Expenses | 21 000 | 46 000 |
| Creditors | 2 300 | 4 600 |
| Loans to members | - | 120 300 |
| Interest due from members | - | 2 100 |
| Loan from Co-operative Union Bank | - | 100 000 |
| Equipment | - | 40 000 |
| Portable stalls | - | 6 500 |
| Inventory | 5 100 | 29 300 |
| Bank | 60 500 | 126 400 |
The co-operative paid out dividends of 10¢ per share in its first year of operation and transferred the remainder to a Members' Education Fund.
[20 marks]
Prepare the Income Statement and the Appropriation Account for Liontown Co-operative for the first year ended 31 December 2010.
[6 marks]
During the second year of operation, Liontown Co-operative began lending money to members who wished to start their own small business.
[4 marks]
Identify the type of co-operative under which Liontown was classified in the operation of its a) first year b) second year.
[2 marks]
Name ONE committee that Liontown is LIKELY to use to carry out its business.
[1 mark]
State ONE purpose of the Members' Education Fund.
[1 mark]
For the year ended 31 December 2011, the Board of Directors records a surplus of $157 500. The board plans to
Prepare a classified Balance Sheet for Liontown Co-operative for the year ended 31 December 2011 (second year of operation) taking the appropriation of the surplus into consideration.
[10 marks]