Free CXC Principles of Accounts Paper 2 May/June 2022 past paper from 2022. Includes a worked answer key. Open the PDF, take a timed test, and study with AI on Caribbean AI.
Answer keys are free on Caribbean AI. View the answers to every past-paper question at no cost - no payment needed - with step-by-step worked solutions and instant AI marking available on Premium.
CSEC Principles of Accounts Paper 2 May/June 2022 - Free CXC Past Paper with Answers
Free CXC Principles of Accounts Paper 2 May/June 2022 past paper from 2022. Includes a worked answer key. Open the PDF, take a timed test, and study with AI on Caribbean AI.
Opening the interactive papers…
Every question from this paper as text. See the answers and worked solutions. Questions are the property of the Caribbean Examinations Council; Caribbean AI is not affiliated with CXC.
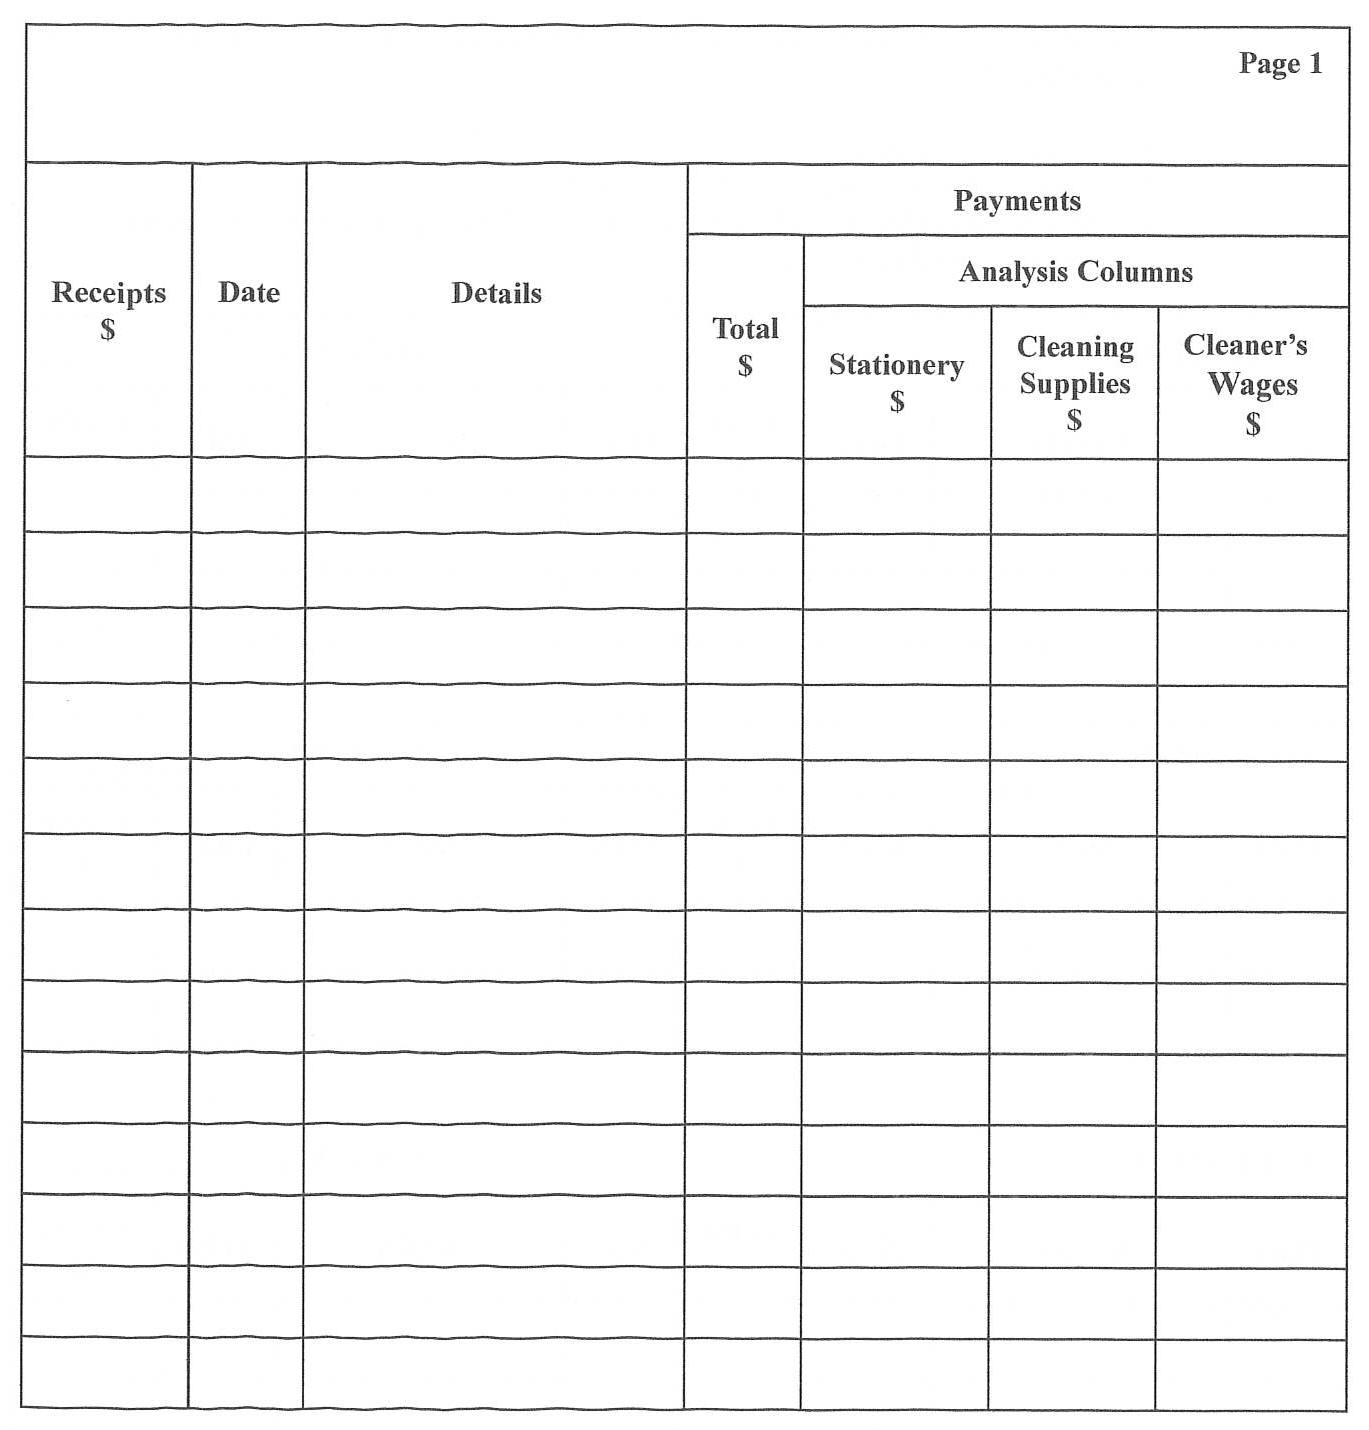
The petty cashier for TD Salon was given $1 500 on 1 April 2022 to start a petty cash book which will be maintained on the imprest system. Analysis columns are provided in the petty cash book for stationery, cleaning supplies and wages.
During the month of April 2022, the following transactions occurred.
[20 marks]
(i) Use the petty cash book form provided on page 3 to record the petty cash transactions for TD Salon for the month of April 2022. (ii) Total, balance and rule the petty cash book at the end of April. (iii) Record the entry in the petty cash book on 1 May 2022 to replenish the petty cash fund.
[9 marks]
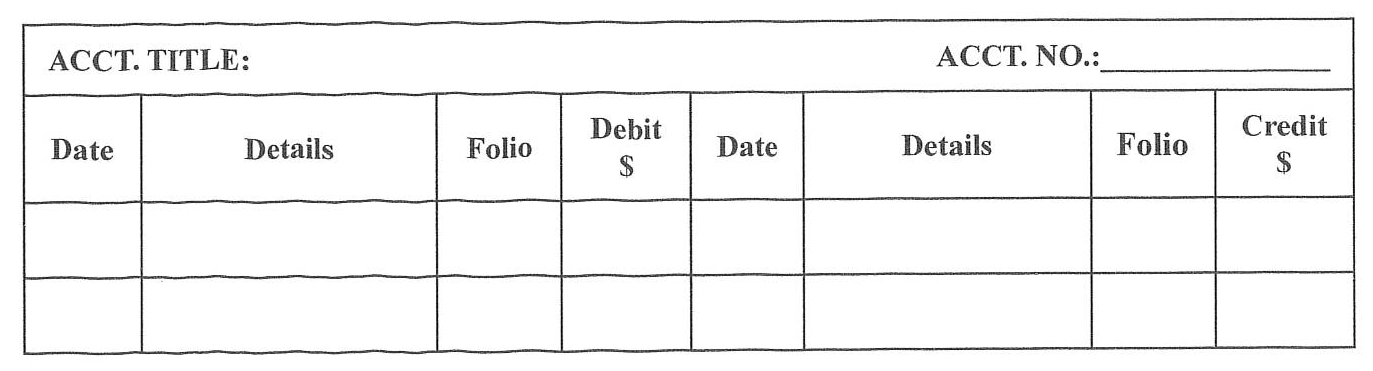
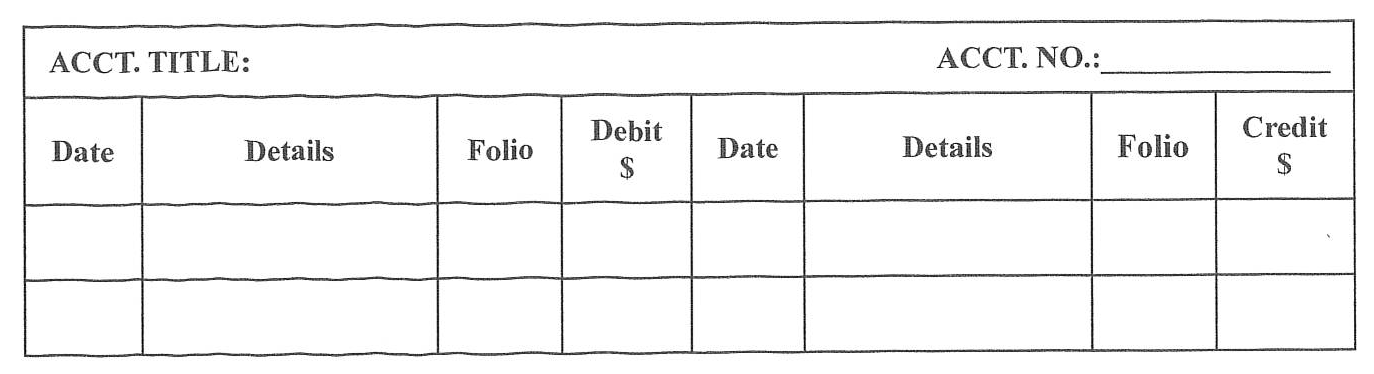
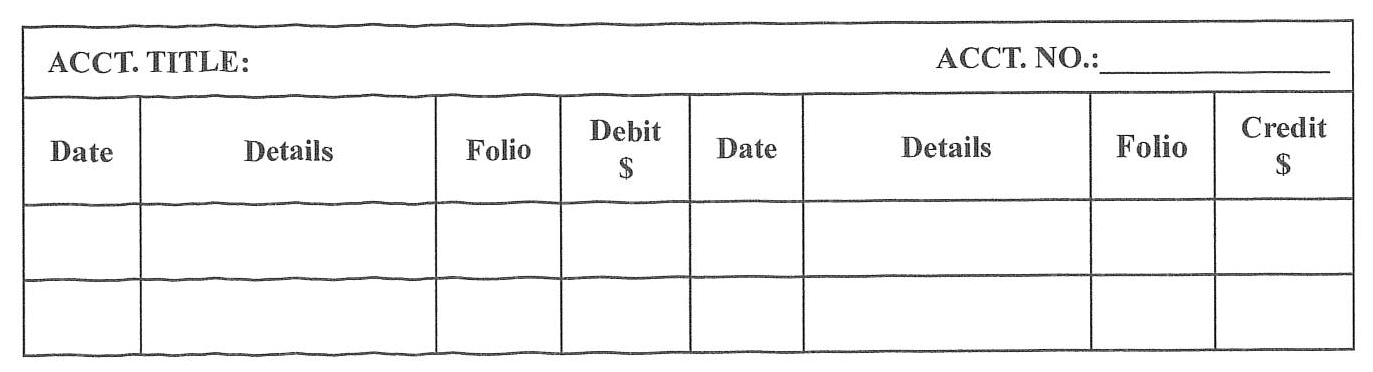
Use the ledger account forms provided below to post the totals from the petty cash book at month end.
[8 marks]
The owner of TD Salon has asked you to prepare and sign the cheque to be given to Turi Francis, the petty cashier, to cash at the bank for the purpose of replenishing the petty cash fund on 1 May 2022. Use the form below to prepare the cheque for this purpose.
[3 marks]
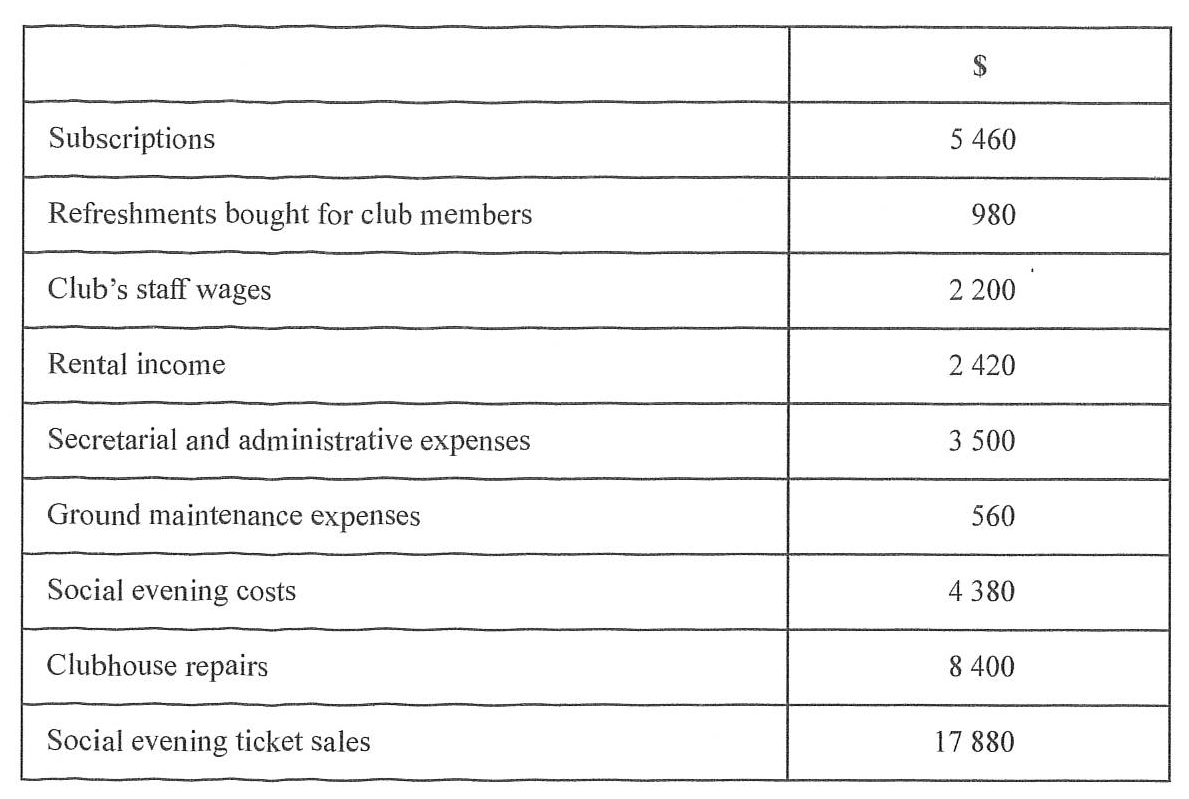
The treasurer of Suri Youth and Sports Club has listed the following details about the club's affairs for the year ended 30 April 2022.
| $ | |
|---|---|
| Subscriptions | 5 460 |
| Refreshments bought for club members | 980 |
| Club's staff wages | 2 200 |
| Rental income | 2 420 |
| Secretarial and administrative expenses | 3 500 |
| Ground maintenance expenses | 560 |
| Social evening costs | 4 380 |
| Clubhouse repairs | 8 400 |
| Social evening ticket sales | 17 880 |
Additional Information
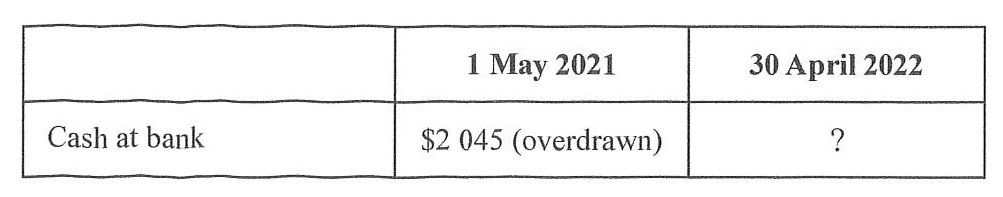
| 1 May 2021 | 30 April 2022 | |
|---|---|---|
| Cash at bank | $2 045 (overdrawn) | ? |
Use the form provided on page 9 to prepare the club's receipts and payments account for the year ended 30 April 2022. Clearly identify the closing balance for the start of the new year.
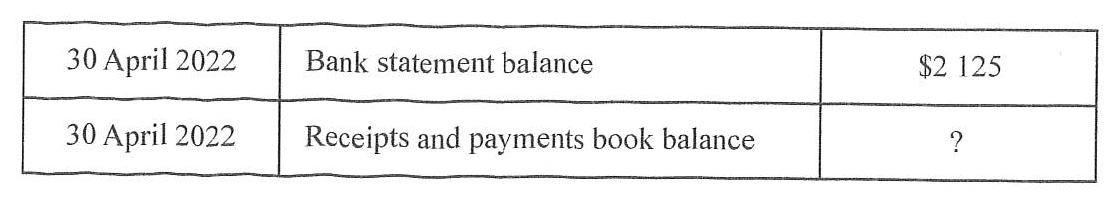
On 30 April 2022, the treasurer of Suri Youth and Sports Club presented the club's financial team with the following information.
| | | |:--------------------------|:-----------------------------------|:----------| | 30 April 2022 | Bank statement balance | $2 125 | | 30 April 2022 | Receipts and payments book balance | ? |
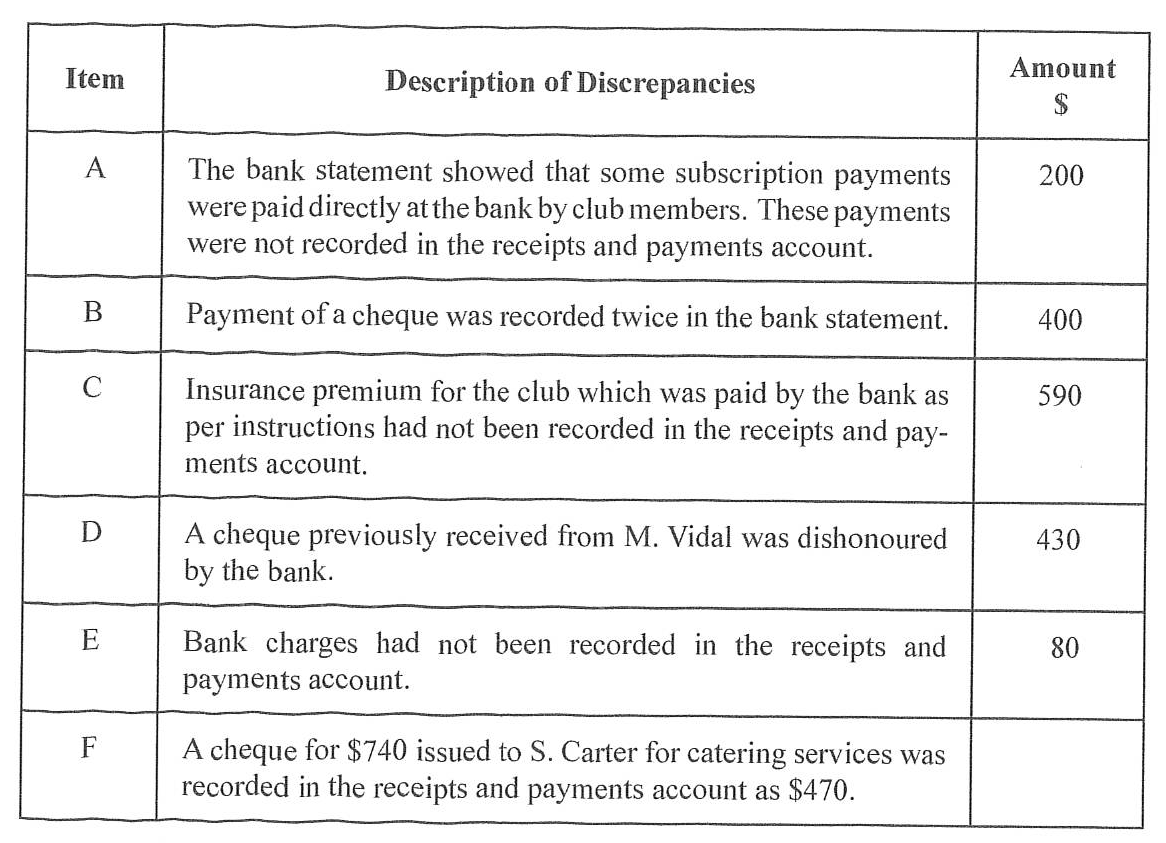
Discrepancies between the two records were discovered as follows.
| Item | Description of Discrepancies | Amount $ |
|---|---|---|
| A | The bank statement showed that some subscription payments were paid directly at the bank by club members. These payments were not recorded in the receipts and payments account. | 200 |
| B | Payment of a cheque was recorded twice in the bank statement. | 400 |
| C | Insurance premium for the club which was paid by the bank as per instructions had not been recorded in the receipts and payments account. | 590 |
| D | A cheque previously received from M. Vidal was dishonoured by the bank. | 430 |
| E | Bank charges had not been recorded in the receipts and payments account. | 80 |
| F | A cheque for $740 issued to S. Carter for catering services was recorded in the receipts and payments account as $470. |
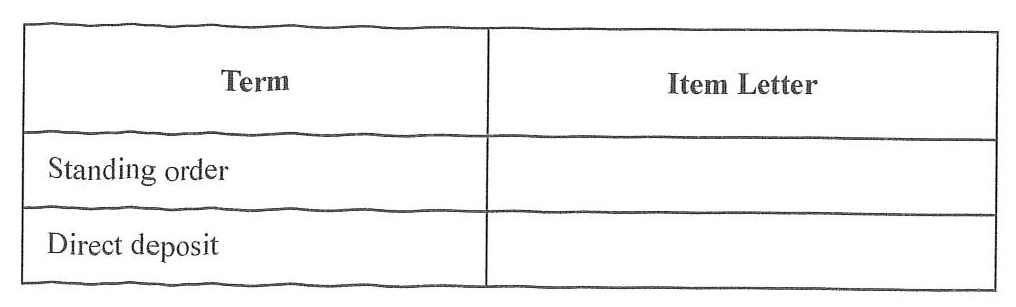
State which of the discrepancies above match the two terms in the following table, by writing the corresponding item letter from the table above in the spaces provided in the table below.
| Term | Item Letter |
|---|---|
| Standing order | |
| Direct deposit |
Prepare the updated receipts and payments account to show the updated cash at bank figure for Suri Youth and Sports Club at 1 May 2022. Begin with your closing cash balance calculated in (a).
[7 marks]
(iii) Prepare a bank reconciliation statement for Suri Youth and Sports Club for the month of April 2022, beginning with your updated cash at bank figure from (b) (ii).
[3 marks]
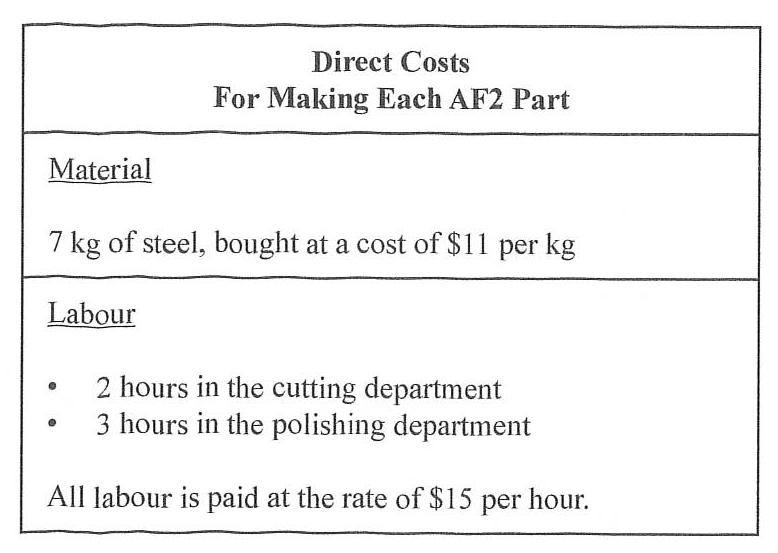
Rayelle Manufacturing Company manufactures automobile parts, model AF2. The following information is available for the direct costs used to manufacture one automobile AF2 part.
| Material | |
|---|---|
| 7 kg of steel, bought at a cost of $11 per kg | |
| Labour | |
| - 2 hours in the cutting department | |
| - 3 hours in the polishing department |
All labour is paid at the rate of $15 per hour.
(a) (i) Calculate the total direct costs of producing one AF2 automobile part.
[25 marks]
Calculate the total direct costs of producing 800 AF2 automobile parts.
[3 marks]
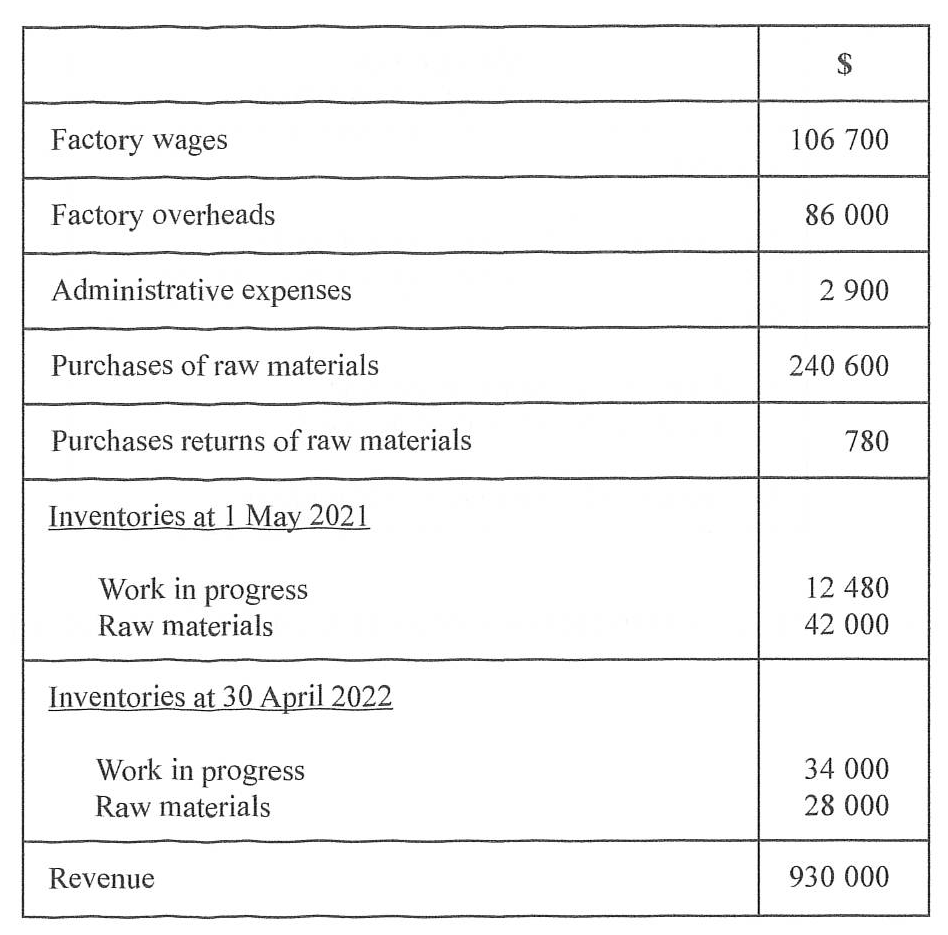
The following information has been extracted from the books of Rayelle Manufacturing Company for the year ended 30 April 2022.
| $ | |
|---|---|
| Factory wages | 106 700 |
| Factory overheads | 86 000 |
| Administrative expenses | 2 900 |
| Purchases of raw materials | 240 600 |
| Purchases returns of raw materials | 780 |
| Inventories at 1 May 2021 | |
| Work in progress | 12 480 |
| Raw materials | 42 000 |
| Inventories at 30 April 2022 | |
| Work in progress | 34 000 |
| Raw materials | 28 000 |
| Revenue | 930 000 |
[12 marks]
Use the information provided in the table on page 14 to prepare an extract, showing calculations to arrive at the cost of raw materials used for the year ended 30 April 2022.
[4 marks]
Prepare the company's manufacturing account to show the total cost of production of manufactured goods for the year ended 30 April 2022.
[8 marks]
During the year ended 30 April 2022, Rayelle Manufacturing Company produced 50 000 AF2 automobile parts.
Use the total cost of production figure from (b) (ii) to calculate the unit cost of producing one AF2 automobile part in the year ended 30 April 2022.
[2 marks]
Payne Ltd has been asked to submit a business plan for the launching of a new product line.
[15 marks]
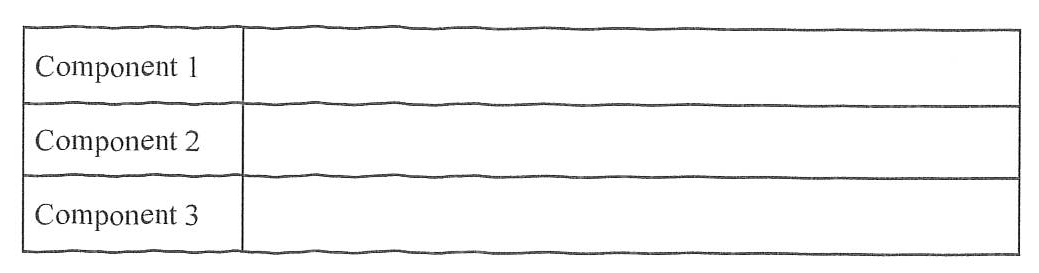
List THREE components Payne Ltd should include in the business plan.
[3 marks]
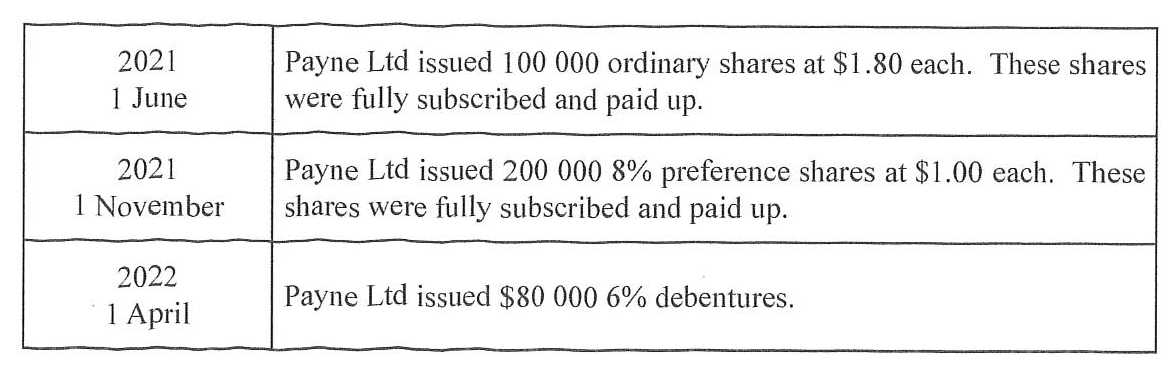
The authorized share capital for Payne Ltd is as follows.
| 2021 | Payne Ltd issued 100 000 ordinary shares at $1.80 each. These shares were fully subscribed and paid up. |
|---|---|
| 1 June | |
| 2021 | Payne Ltd issued 200 000 8% preference shares at $1.00 each. These shares were fully subscribed and paid up. |
| 1 November | |
| 2022 | Payne Ltd issued $80 000 6% debentures. |
| 1 April |
Use the form provided on page 19 to prepare journal entries to record the three transactions above for Payne Ltd. Narratives are not required.
[6 marks]
Use the information presented in the issue of shares on page 18 to prepare an extract showing the shareholders' equity section of Payne Ltd's statement of financial position as at 30 April 2022.
[6 marks]
During the financial year ended 30 April 2022, Payne Ltd declared and paid an ordinary dividend of 5¢ per share and paid out the dividend due on the preference shares.
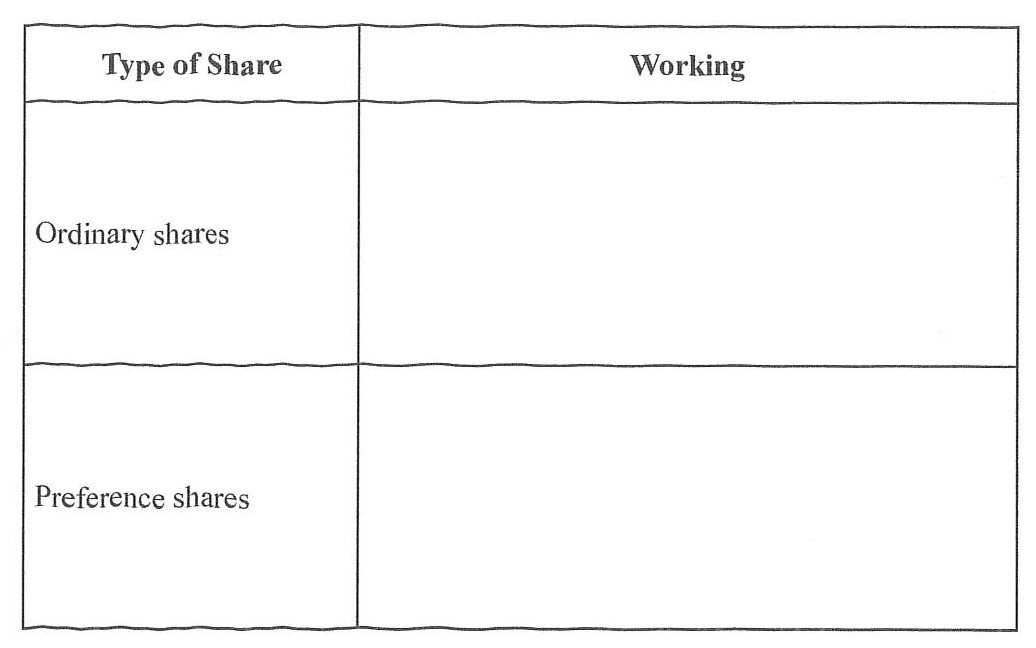
For EACH type of share specified in the table below, calculate the amount the company paid out in dividends for the year ended 30 April 2022.
[3 marks]
Payne Ltd is planning to raise additional capital through another issue of shares. <br/> (i) Calculate the additional number of 8% preference shares that the company can issue. (ii) Calculate the total value of these additional preference shares.
[2 marks]
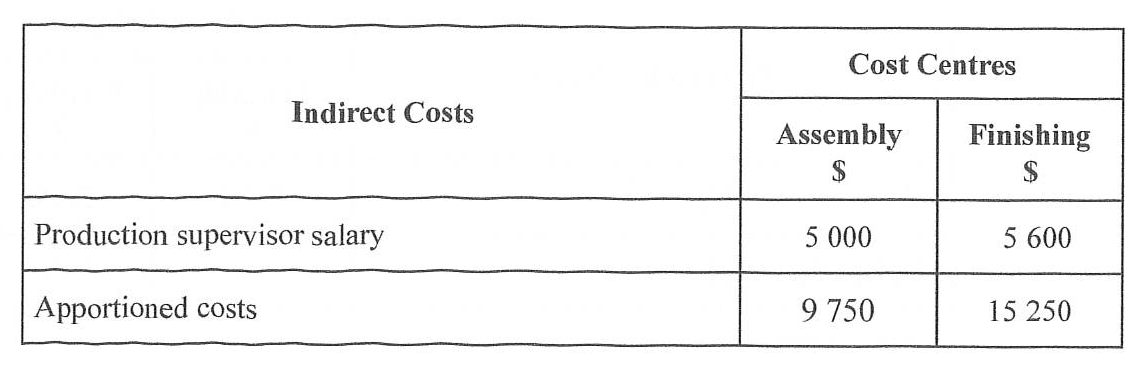
High Tech Limited is a manufacturer of Scalextric toy cars. It has two cost centres, assembly and finishing, and information is available as follows.
| Cost Centres | |
|---|---|
| Indirect Costs | Assembly |
| $ | |
| Production supervisor salary | 5 000 |
| Apportioned costs | 9 750 |
(a) Use the information given in the table above to calculate the total indirect costs for EACH cost centre.
[2 marks]
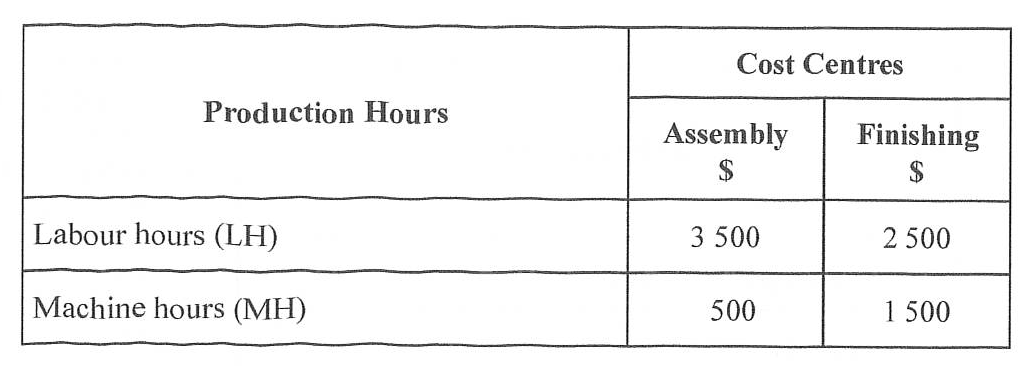
The total production hours for the business are as follows.
| | Cost Centres | | :---------------- | :----------- | :----------- | | Production Hours | Assembly | Finishing | | | $ | $ | | Labour hours (LH) | 3 500 | 2 500 | | Machine hours (MH) | 500 | 1 500 |
Additional Information
(i) State the formula to calculate the overhead absorption rate (OAR). (ii) Calculate the overhead absorption rate (OAR) for EACH cost centre.
| Assembly Cost Centre | Finishing Cost Centre |
|---|---|
[7 marks]
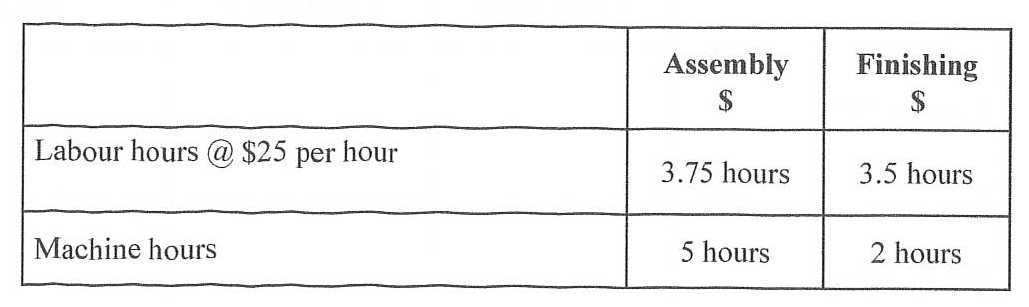
High Tech Limited has received an order for some Scalextric toy cars. The production of ONE toy car requires the use of 5 kg of direct material which is purchased at $10 per kg. The breakdown of the remaining production details is as follows.
| Assembly | Finishing | |
|---|---|---|
| $ | $ | |
| Labour hours @ $25 per hour | 3.75 hours | 3.5 hours |
| Machine hours | 5 hours | 2 hours |
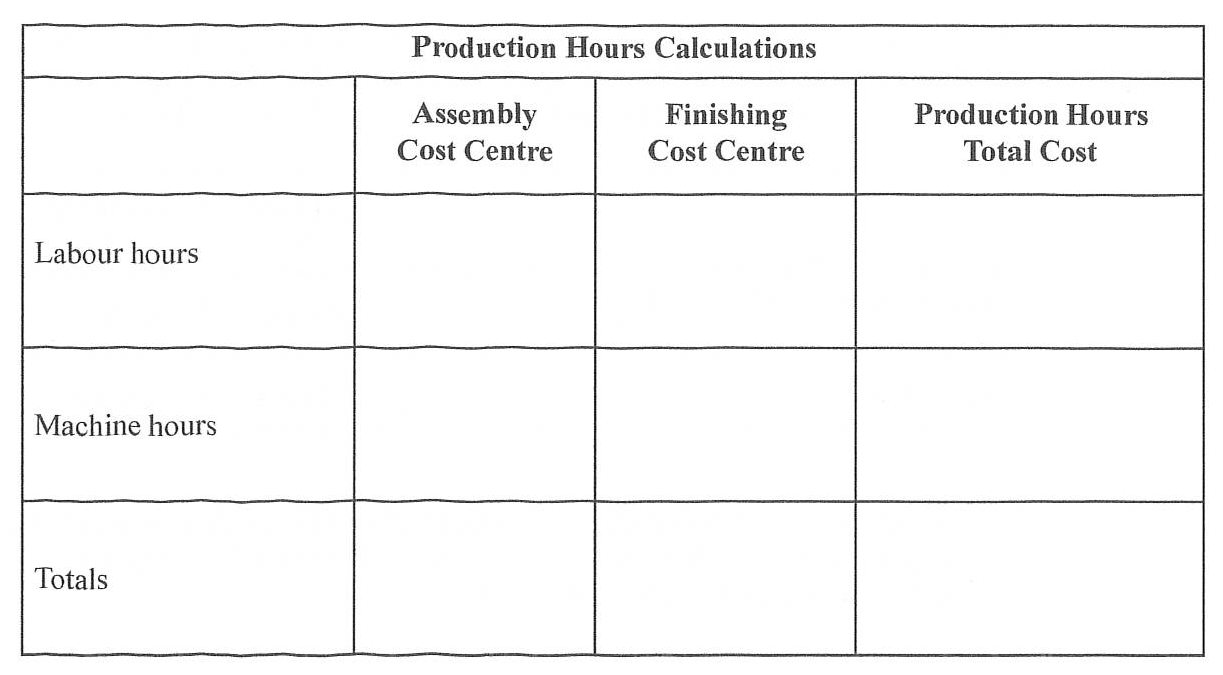
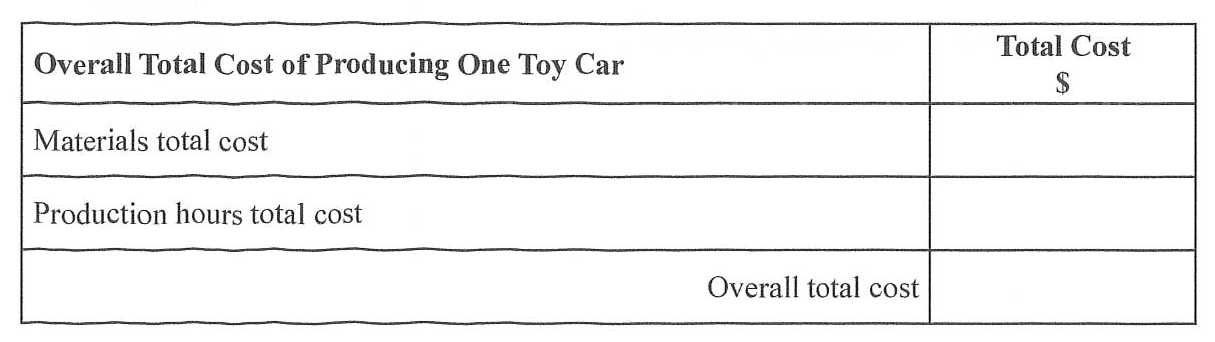
Use the spaces provided in the tables on pages 25 and 26 to calculate and arrive at the total cost of producing ONE Scalextric toy car. Remember to apply your previously calculated OARs for the two cost centres appropriately.
| Direct Materials Calculations | Materials Total Cost |
|---|---|
| $ | |
| | Production Hours Calculations | | | :------------ | :-------------------- | :------------------ | :---------------- | | | Assembly Cost Centre | Finishing Cost Centre | Total Cost | | Labour hours | | | | | Machine hours | | | | | Totals | | | |
| Overall Total Cost of Producing One Toy Car | Total Cost |
|---|---|
| Materials total cost | $ |
| Production hours total cost | |
| Overall total cost |
High Tech Limited has a 50% mark-up policy. (i) Define the term 'mark-up pricing'. (ii) Calculate the total dollar value of the mark-up on ONE Scalextric toy car. (iii) Calculate the selling price of ONE Scalextric toy car.
[2 marks]
[2 marks]
[6 marks]